Key Takeaways
- Corporate bank account applications have a lengthy and complicated process
- Banks have an extensive screening process to filter out any companies that are deemed risky
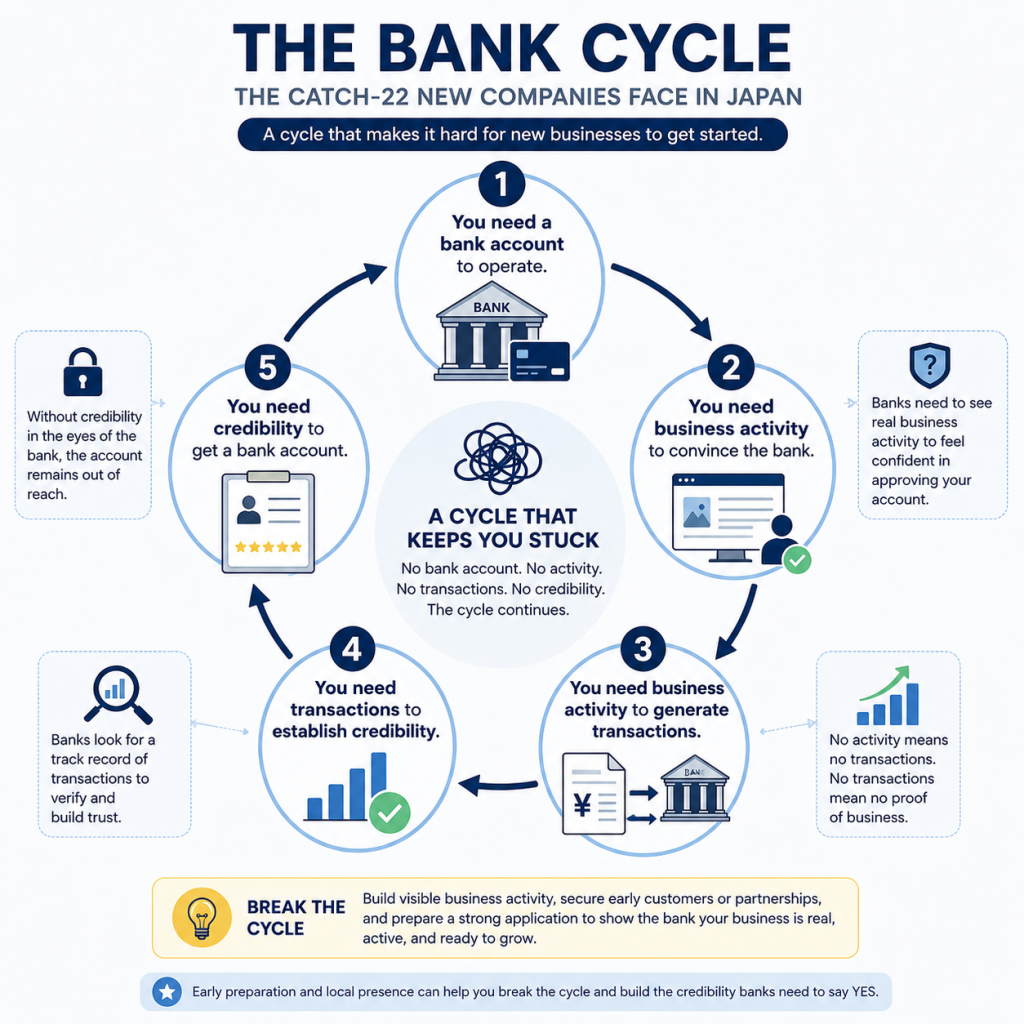
- There is a cycle of credit and applications that most founders get caught up in
- There are steps to take that will solidify a company and improve the likelihood of getting approval
In the case of many entrepreneurs looking to establish a presence in Japan, registering a company is surprisingly simple. However, getting a bank account in Japan can prove to be a little less straightforward.
A bank can decline a corporate-account application even when the company is legally registered. The bank must understand the applicant, beneficial owners, business, purpose of the relationship and expected use of the account. It may request additional evidence according to the risks involved.
A rejection does not prove that one specific document or fact caused the decision. Review the complete application for unclear ownership, unsupported business activity, inconsistent information, unexplained funds or transactions, office and contact issues, and missing evidence before deciding whether to reapply.
Why is opening a corporate bank account in Japan so difficult for foreign entrepreneurs?
As a foreign founder, you might find unique challenges that do not apply to Japanese citizens. Rejection is often driven by risk management and regulatory compliance rather than discrimination or business quality.
Japanese banks are known for their very conservative means of operating. In order to combat fraud and financial crimes, anti-money laundering (AML) and Know Your Customer (KYC) requirements have become increasingly strict. This forces banks to dive deep when faced with new, unknown companies. This becomes hard when foreigners apply for a bank account because of the limited visibility into overseas owners, international transactions, and cross-border corporate structures.
It is common for entrepreneurs to believe that this acceptance from the banks is based primarily on their nationality. When in reality, banks are primarily focused on reducing risk. Their goal is to ensure they understand everything about the company, such as who owns the company, how it operates, where money comes from, and whether future transactions can be monitored effectively.
What Japanese banks need to verify
Banks conduct customer and business verification before opening a corporate account. The exact questions and evidence vary, but an application normally needs to make the following areas understandable and consistent:
- The company’s registered identity and address
- The beneficial owners and ownership chain
- The actual business activity and account purpose
- The source of capital and other funds
- Expected customers, counterparties, countries, currencies, amounts and transaction frequency
- The person authorized to operate the account
- The relationship between the company, its representative and Japan
- Consistency between the application, website, business plan, contracts and supporting records
Clear evidence can reduce avoidable questions, but it does not guarantee that a bank will accept the application.
Corporate Bank Accounts
Prepare a Stronger Corporate Bank-Account Application
- Documents structured for Japanese bank review from day one.
- Guidance on business plan, ownership structure, and local presence.
- Trusted by 100+ companies incorporated across Japan.
Why do Japanese banks reject corporate bank account applications?
| Possible concern | Evidence that may help | What can be corrected | Important limitation |
|---|---|---|---|
| Unclear ownership | Ownership chart, shareholder records and beneficial-owner identity | Reconcile ownership across every form and document | The bank decides whether verification is sufficient |
| Vague business purpose | Website, business plan, contracts, proposals or product material | Explain the customers, service, revenue model and Japan activity consistently | A legal business is not automatically bank-eligible |
| Unclear source of funds | Capital-transfer records and a source explanation | Trace the money and explain unusual transfers | Never create or alter evidence after the fact |
| Limited evidence of real operations | Contracts, invoices, website, licence and office evidence where relevant | Supply objective evidence that the business is active or ready to operate | An office does not guarantee approval, and a virtual office is not an automatic rejection |
| Expected transactions are unclear | Expected counterparties, countries, currencies, amounts and frequency | Align the expected activity with the business model | Activity may be monitored after opening |
| Representative or account operator is unclear | Identity and authority documents | Confirm who is authorized and how the bank can contact that person | Requirements differ by bank and application route |
| Communication problems | Clear Japanese explanations where needed | Prepare terminology and consistent answers | Do not assume that an interpreter is accepted |
| Documents conflict | Cross-check names, addresses, owners, activities and forecasts | Correct inconsistencies before applying | Never hide a discrepancy |
| A previous application was rejected | Previous application, later requests and evidence of material changes | Reapply after correcting identifiable gaps or choosing a more suitable route | Reapplication is independently reviewed |
Are virtual offices automatically rejected?
Many startup founders choose virtual offices to reduce costs. Banks may examine these applications more carefully because the registered address does not itself demonstrate where the company operates. However, a virtual office is not an automatic rejection. GMO Aozora’s own guidance says that a company registered at a virtual-office address may apply. Approval still depends on the complete application, including the business activity, supporting evidence, representative, expected transactions and address.
Why foreign founders often struggle with the “No Japanese Track Record” problem
How Japanese banks build trust
One of the most misunderstood aspects of Japanese banking is that overseas success does not automatically transfer into Japan. A founder could have a successful business overseas, significant revenue, etc. But banks often evaluate the company in almost every respect. Trust is frequently built through Japanese customers, business partners, suppliers, and phone numbers. This emphasis on local credibility reflects Japan’s broader business culture, which prioritizes stability, predictability, and long-term relationships.
How can foreign entrepreneurs improve their chances of approval?
Preparation before applying is often the biggest determinant of success. Once the first wall is broken, opportunities become increasingly easy to obtain.
Establish a strong local presence
Establishing a local presence builds a foundation for proof that a company is legitimate and has ties to the local community. Some ways to do this include securing an appropriate office arrangement, obtaining a Japanese business phone number, and preparing Japanese-language materials.
Create a realistic and detailed business plan
Another way to build trust is through financial transparency. This includes explaining revenue generation clearly, providing achievable financial projections, and demonstrating understanding of the Japanese market. This transparency is often the major distinction between safe and unsafe companies to Japanese banking officials.
Prepare for enhanced compliance reviews
Compliance reviews also allow Japanese banks to see into the operations of a startup company. Some ways to prepare for compliance reviews are to organize ownership documentation, anticipate and have an answer for AML related questions, and explain cross-border transaction flows clearly.
Seek professional assistance when necessary
Help is almost always available, and a lot of times necessary. Some professional help might include help from people like administrative scriveners, tax accountants, and business consultants specializing in foreign companies.
Supporting evidence of business activity
Documentation checklist:
- Revenue forecasts
- Client contracts or letters of intent
- Supplier agreements
- Invoices and purchase orders
- Clear and realistic business plans
- Revenue forecasts supported by evidence
- Japanese-language business materials
- Operational readiness
- Company registration certificate
- Articles of incorporation
- Identification documents for directors
- Proof of office address
Building a credible online presence
While having an established presence within Japan is important, an online presence is also necessary and goes hand in hand with setting a foundation for business. Simply having a website is not enough. Banks may review customer references, Japanese language content, and founder information.
What should you do if your application is rejected?
Prepare before applying
Use this path when the company has not applied yet and important evidence is missing or inconsistent. Complete the ownership, funds, business-activity, transaction and authority explanations before selecting an application route.
Reapply after a material improvement
Reapply when an identifiable weakness has been corrected and the target bank or application route still fits the company. Submitting the same evidence again without a meaningful change is unlikely to resolve the original uncertainty.
Seek help when the problem is unclear
Get assistance when the company cannot identify the likely weakness, the ownership or transaction structure is complex, or a bank’s request is difficult to interpret. Assistance can improve preparation, but it cannot guarantee acceptance.
Corporate bank-account application checklist
- Can we identify every beneficial owner and explain the ownership chain?
- Can we trace and explain the source of the company’s capital and other funds?
- Does the business plan clearly explain the product, customers, pricing and revenue model?
- Do we have objective evidence such as contracts, proposals, invoices, licences or customer communication?
- Can we explain where the company operates and how the address is used?
- Can we describe expected counterparties, countries, currencies, amounts and transaction frequency?
- Are the website, application, registration, contracts and forecasts consistent?
- Is the account operator’s authority and identity clear?
- Can the relevant person explain the business consistently in the required language?
- If a previous application was rejected, has something material changed before reapplying?
This checklist identifies preparation gaps. It does not predict approval. Use SmartStart’s bank-account readiness checker for a guided review, or speak with the support team if the ownership or transaction structure is complex.
Missing documents banks actually want?
- Document package built to match bank expectations.
- Business plan reviewed before you submit anything.
- 60+ visas granted for founders like you.
Frequently Asked Questions About Japanese Corporate Bank Account Rejections
Why do corporate bank-account applications get rejected?
Banks do not normally disclose their complete internal reasoning. Common areas to review include ownership, business purpose, operating evidence, source of funds, expected transactions, authority, communication and inconsistencies between documents.
Can I use a virtual office?
Some banks accept applications from companies registered at virtual-office addresses, but the arrangement may receive additional scrutiny. Provide clear evidence of the company's activity, customers, transactions and operating arrangements. Acceptance of the address does not guarantee account approval.
Which bank is best for a foreign-owned company?
There is no universal best bank. The appropriate route depends on the company, representative, business model, location, transactions, currencies and service requirements. See Scaling Your Company's corporate banking guide for a broader bank-selection framework. For one online-bank route, see SmartStart's GMO Aozora corporate-account guide.
Finished the guide?
Check your bank account readiness
Start the readiness check